2026 Commodity Demand Review: Volume, Price Compared to 2025, And Next Year’s Forecast
Less wheat, corn and cotton crossed borders in 2026 than in 2025, and all three got more expensive anyway. Wheat is up 36.7% on the year while 14.69 million tons less of it are moving. That happened because Russia and Ukraine are shipping less through the Sea of Azov and the Black Sea, and because El Niño is sitting over India and Thailand as the 2026/27 harvests come in. Below are 8 commodities with what moved and what it cost, September 2025 against September 2026.
Volumes for wheat, corn, soybeans, rice and cotton are world trade from USDA WASDE-674, 12 August 2026, and the 2026 figures are projections USDA revises monthly. Prices are ICE and CBOT closes from Trading Economics on 11 September 2026. The 2025 prices are worked backwards from those closes and the published year on year percentages, so they are approximate.
| Product | Volume 2025 | Volume 2026 | Price Sep 2025 | Price Sep 2026 | Change |
|---|---|---|---|---|---|
| Wheat | 227.40 mt | 212.71 mt | ~$5.23 /bu | $7.16 /bu | +36.7% |
| Corn | 220.73 mt | 210.48 mt | ~$4.30 /bu | $5.12 /bu | +19.1% |
| Soybeans | 187.19 mt | 190.41 mt | ~$10.46 /bu | $12.98 /bu | +24.0% |
| Rice | 60.32 mt | 62.78 mt | ~$11.50 /cwt | $15.63 /cwt | +35.9% |
| Cotton | 45.56 m bales | 43.82 m bales | ~$0.65 /lb | $0.88 /lb | +34.7% |
| Sugar | 1.1 mt surplus | 0.2 mt deficit | ~$0.16 /lb | $0.18 /lb | +16.7% |
| Cocoa | not published | not published | ~$7,528 /t | $5,962 /t | -20.8% |
| Coffee | 118.43 m bags | 118.39 m bags | ~$4.00 /lb | $2.91 /lb | -27.2% |
Wheat
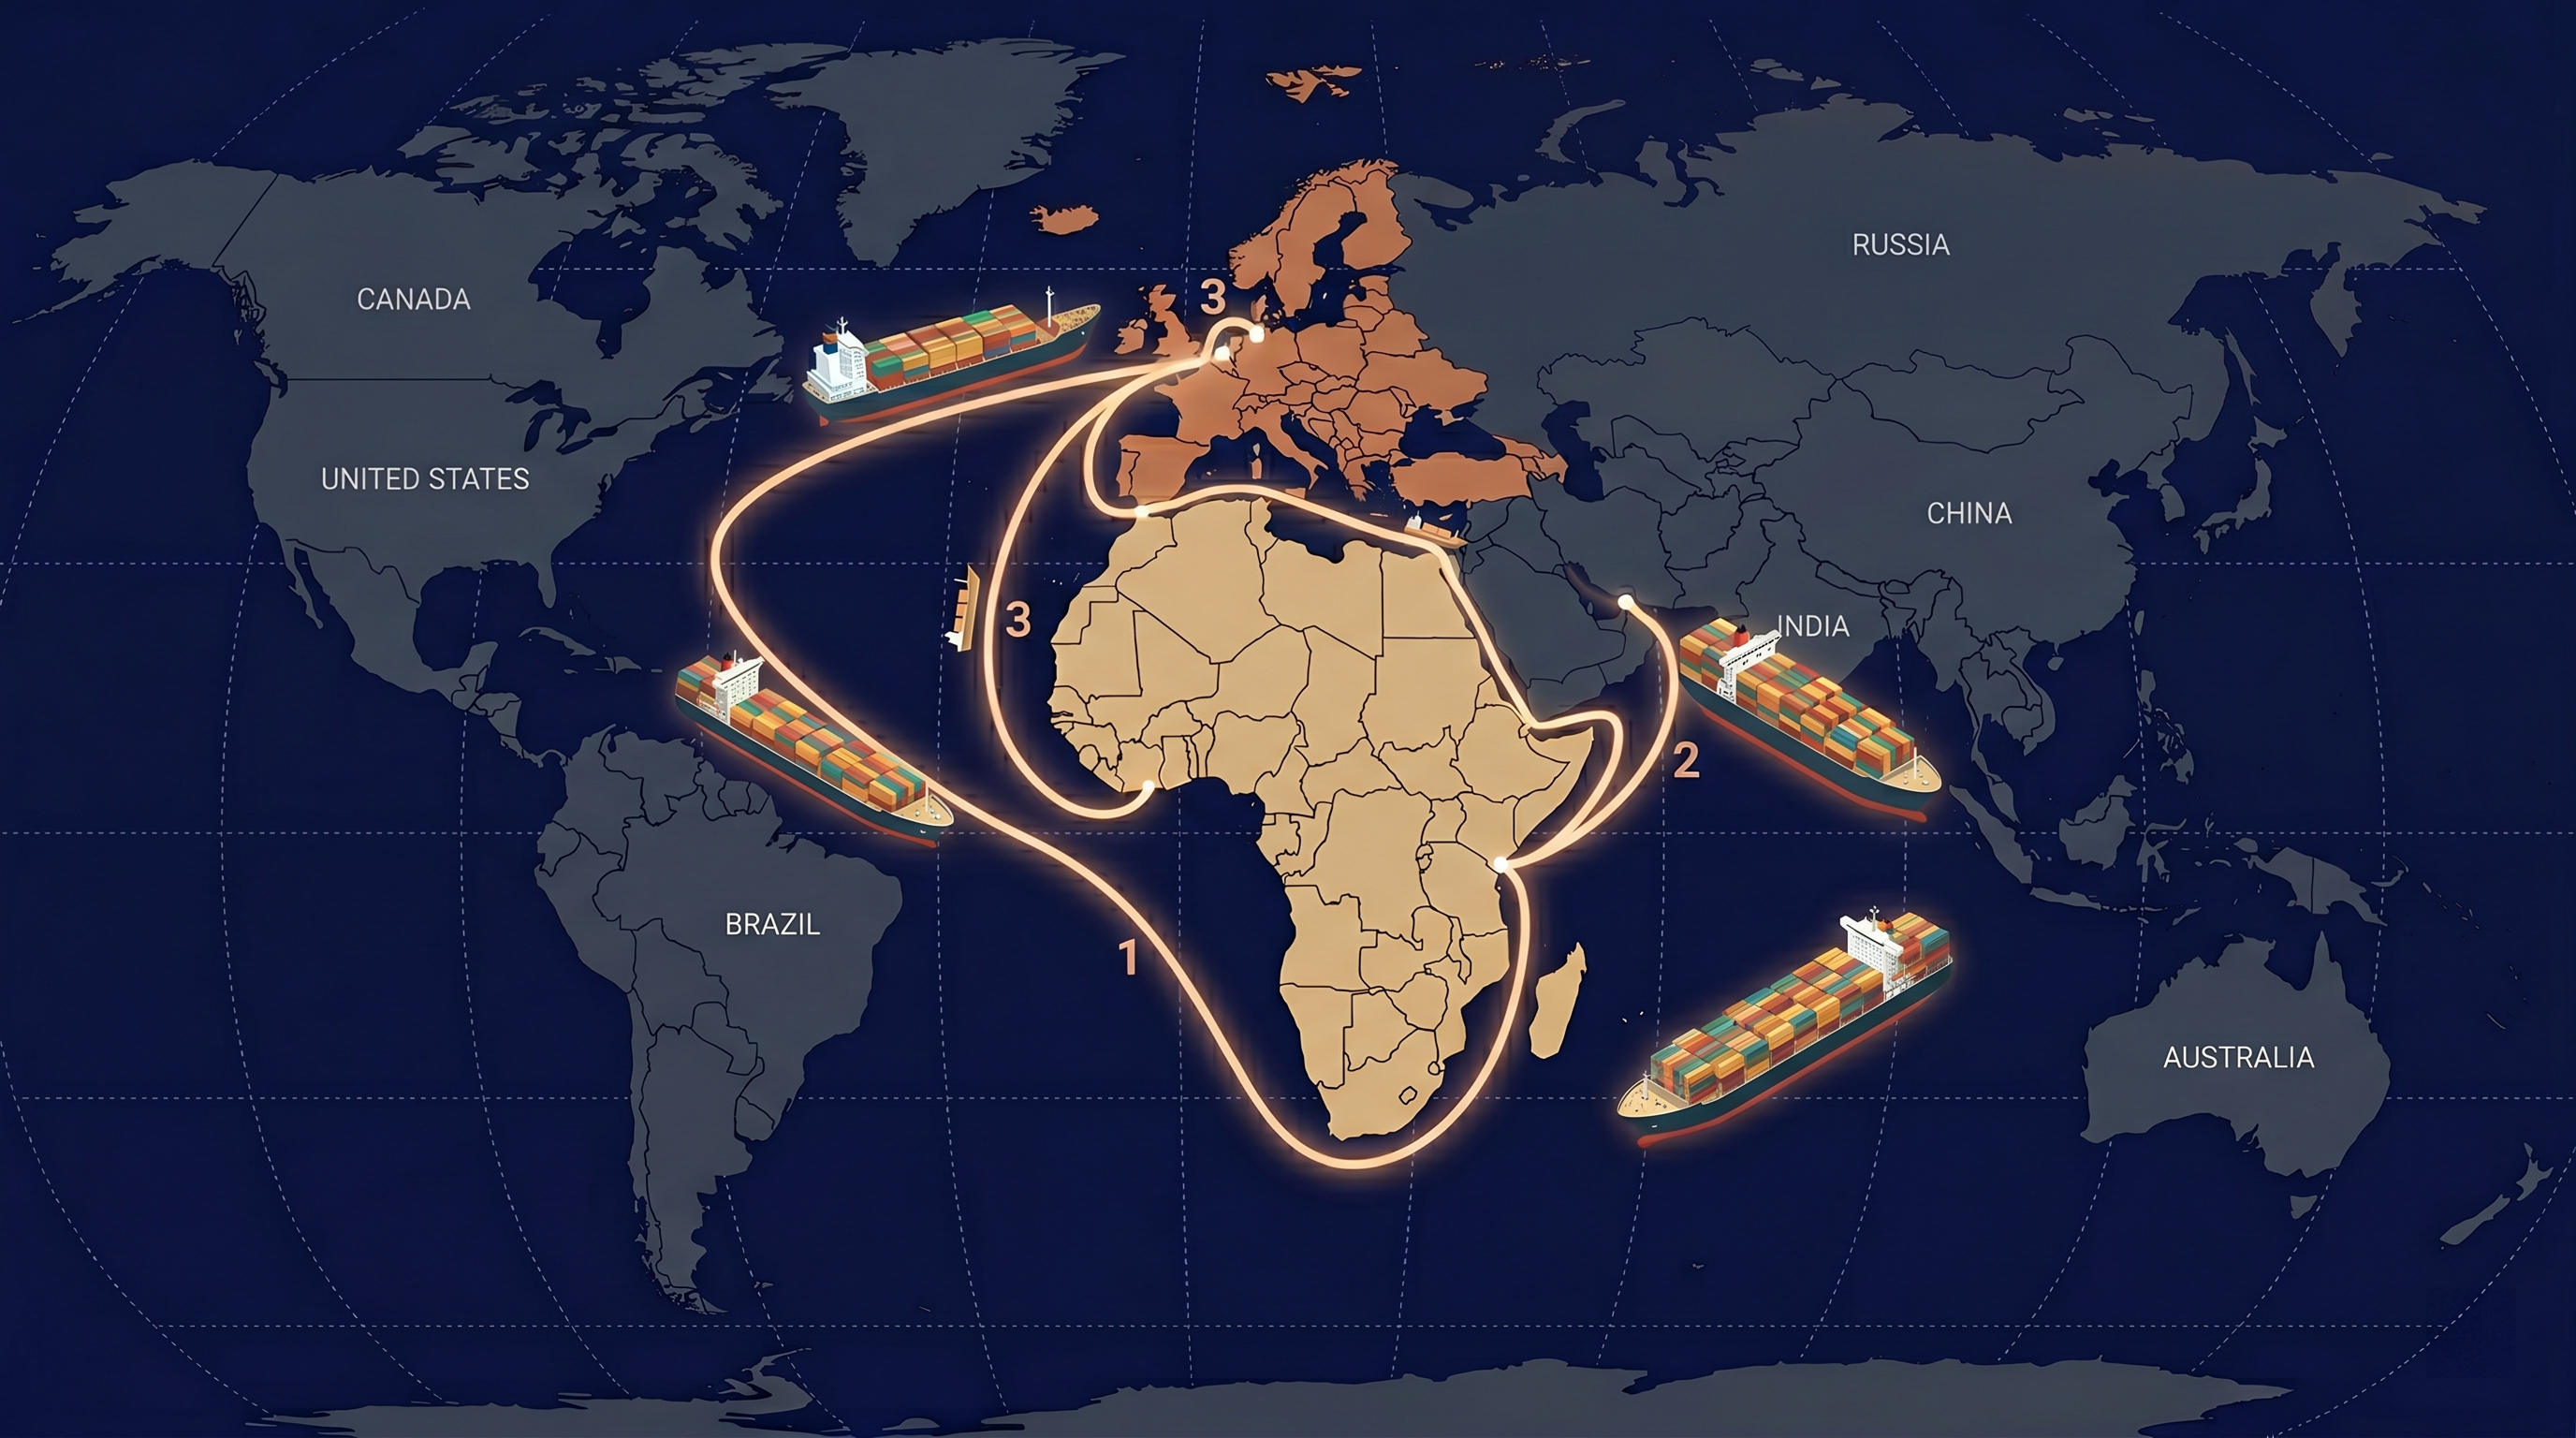
212.71 million tons are forecast to move this season against 227.40 last season, and the price rose 36.7%. USDA names the cause directly, Russia and Ukraine exports are lower on disruption in the Sea of Azov and the Black Sea. The contract hit $7.70 per bushel on 28 August, the highest since early 2023, then fell back when Russia named Abu Dhabi as a venue for talks.
Corn
Trade drops to 210.48 million tons from 220.73, and the price rose 19.1%. The US crop is the second largest ever recorded at 16.013 billion bushels, and the price still climbed, because USDA cut the yield forecast 2.3 bushels per acre in August and Ukraine cannot ship its normal volume. USDA raised US corn exports 75 million bushels to 3.3 billion to cover the gap.
Soybeans
The only grain here where volume rose, 190.41 million tons against 187.19, with the price up 24%. China bought around 1 million tons of US beans in one week in early September, which takes them close to half of the 25 million tons a year they committed to buy through 2028.
Rice
62.78 million tons against 60.32, with the price up 35.9%. You are paying a third more per ton to move more rice than last year. A 5,000 ton order is about 110,231 hundredweight, so at these prices it moves from roughly 1.27 million dollars in September 2025 to roughly 1.72 million dollars now. Note that the CBOT contract prices rough rice, which is paddy before milling, so a milled rice buyer pays a different number.
Cotton
43.82 million bales against 45.56, with the price up 34.7%. Brazil harvested 88.7% of its crop early under heat and drought, Indian monsoon rainfall came in 16% below normal in August, and Cyclone Eduardo hit West Texas during boll development.
Sugar
ISO has the market going from a 1.1 million tonne surplus in 2025/26 to a 200,000 tonne deficit in 2026/27, with production down 1% to 180.1 million tonnes. Thai production is expected to fall at least 17% to below 10 million tonnes, and the EU Sugar Market Observatory forecasts EU production down 19% to 13.4 million tons. The price is the highest since April 2025.
Cocoa
5,962 dollars a tonne against an all time high of 12,906 in December 2024, so down 20.8% on the year and still more than double where the chocolate industry built its costing. Ivory Coast shipped 2.14 million tonnes to port between 1 October 2025 and 30 August 2026, up 19% on the same period last year. ICCO has withheld world production and grindings for 2025/26, which is why the volume columns are empty.
Coffee
118.39 million bags exported October through July against 118.43 million a year earlier, so the volume did not change and only the price did. Note that this 27.2% fall is the New York arabica contract. The ICO Composite Indicator Price, which blends all 4 origin groups, has August 2026 at $2.87 per pound against $2.97 per pound in August 2025, a fall of about 3%.The ICO index blends robusta in with the three arabica groups, so it moved far less than the New York contract did.
.
2027 Forecast
Sugar, ISO has 2026/27 in deficit and Trading Economics models put the price at $0.20 per pound in 12 months against $0.18 today. El Niño is forecast to run through February 2027, so Indian and Thai crop damage stays possible into next year's harvest.
Wheat, US production is forecast at 1,531 million bushels with ending stocks down 22% to 717 million, and USDA raised the season average farm price 20 cents to 6.20 dollars. World ending stocks are projected at 273.25 million tons against 280.22 last season.
Corn, world ending stocks are projected at 274.7 million tons and USDA raised the US season average price 10 cents to 4.50 dollars.
Soybeans, world ending stocks are projected at 124.2 million tons, the US farm price is held at 11.40 dollars, and USDA expects US exports to recover to 1.630 billion bushels as the tariff drag on China eases.
Cotton, world ending stocks are projected at 69.7 million bales, a stocks to use ratio of 56.7%, with consumption raised almost 1 million bales to 122.9 million on China, India, Vietnam and Indonesia.
Rice, world trade for 2026/27 is unchanged at 62.78 million tons with ending stocks at 192.6 million.
Cocoa has no published 2027 forecast, because ICCO has not released current season data. Ivory Coast is separately aiming to lift its own grinding capacity to 1.3 million tonnes in 2026/27 from 650,000 in 2025/26, which moves where beans are processed rather than how many there are.
Coffee has no published 2027 trade forecast we could verify.
Finally
Every price rise on this list was caused by something that happened at origin, a blocked port, a failed monsoon, a cyclone over a cotton field. None of it was caused by buyers wanting more. At ASAFI we buy directly from origins and work with farmers rather than middle men, and supplying commodities globally means we see a harvest problem when the farmer sees it, not when it reaches the contract.
If you are pricing 2027 contracts, sugar tenders covering the Indian and Thai crop should be priced above $0.18 per pound, wheat positions need a Black Sea clause, and cocoa needs repricing the month ICCO restarts publishing.
Sources
Barchart — Ivory Coast port arrivals to 30 August 2026, and Conseil du Café-Cacao grinding capacity target
USDA World Agricultural Supply and Demand Estimates, WASDE-674, 12 August 2026 — world trade, production, ending stocks and US farm prices for wheat, corn, soybeans, rice and cotton
Trading Economics, 11 September 2026 — ICE and CBOT closes and year on year changes for all 8 commodities, plus the 12 month sugar model forecast
International Coffee Organization, Coffee Market Report — export volumes October 2025 to July 2026, and the Composite Indicator Price for August 2026 and August 2025
International Cocoa Organization, Quarterly Bulletin of Cocoa Statistics, August 2026 — confirmation that 2025/26 production and grindings are withheld
International Sugar Organization, via Trading Economics, 2 and 8 September 2026 — 2026/27 balance, production forecast, Thai and EU output